All Categories
Featured

Evaluating Medicare Supplement Plans
Table of Contents
Offered Development OptionsUnderlying Charge StructureParticipating Loan RatesCompany Reputation (given that much of the above will not be ensured)Given that IUL cap rates, participation rates, and loan rates have actually been a moving target fluctuating wildly, we did not want to post actual numbers just to have them end up being outdated a month or 2 later on.
Educational only. Indexed Universal Life policies involve costs, caps, participation rates, spreads, policy charges, and loan threat. Index credits are not guaranteed. Policy loans and withdrawals might reduce money value and survivor benefit, might trigger the policy to lapse, and might produce taxable earnings if not managed effectively. This analysis represents the author's professional viewpoint based upon 19 years of experience and ought to not be considered tailored monetary recommendations for your personal circumstance.
Upgraded September 13, 2026Searching for the "finest IUL companies" or the "finest IUL policies for money build-up" in 2025? You're not alone. Indexed Universal Life (IUL) insurance has acquired substantial attention as a monetary tool that combines a survivor benefit with the capacity for money value development linked to market indexes, typically pitched as a component of a retirement technique.
Medicare Part D Enrollment Guide
The ideal policy and business depend completely on your distinct financial objectives, risk tolerance, health, and timeline. And if you are setting up an SBA loan for your service, our guide to Life insurance for an SBA loan discusses how loan providers see life coverage along with the debt. Comprehending IUL requires browsing a landscape of caps, floors, participation rates, fees, and complex illustrations.
That's where goal, independent guidance ends up being invaluable. Welcome to Insurance Coverage By Heroes. We're an independent insurance coverage agency founded by a former first responder and military spouse, and staffed by specialists with backgrounds rooted in public service. Our mission isn't just to sell insurance; it's to serve and inform our clients, helping them browse intricate financial products like IUL.
This independence permits us to objectively go shopping the market, compare the very best IUL products available, and tailor protection specifically to your individual requirements and objectives. We believe in discovering the ideal suitable for you, not pressing a one-size-fits-all service. Our universal life insurance guide describes the more comprehensive options in this classification.
Burial Insurance Guide
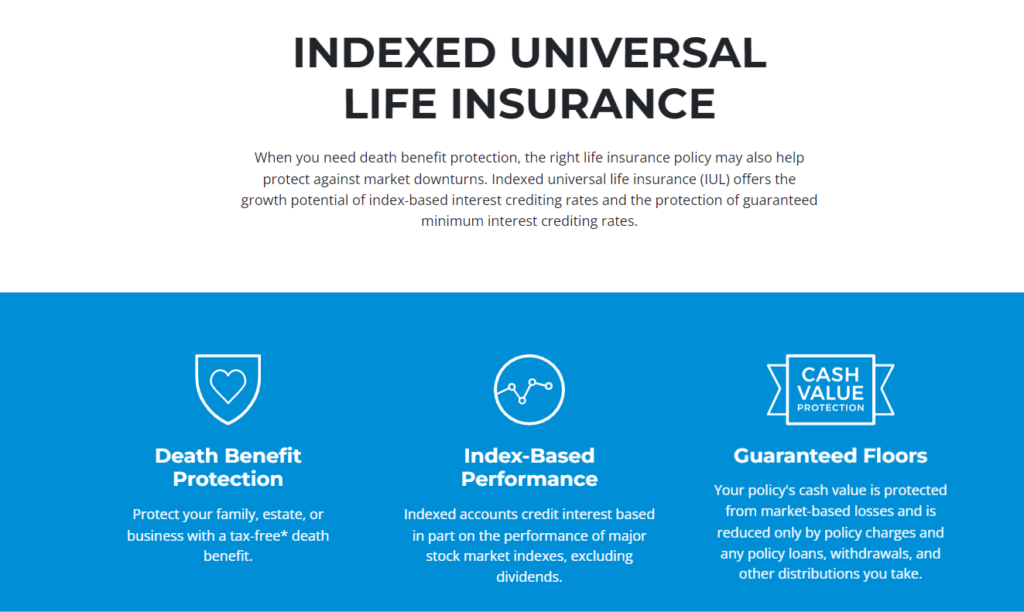
At its core, Indexed Universal Life is a type of permanent life insurance coverage policy. Unlike term insurance, which covers you for a particular duration, long-term policies like IUL are created to last your whole life time, supplied premiums are paid and the policy stays in force. IUL policies have several key parts: This is the primary function of any life insurance coverage policy.
IUL provides flexibility in survivor benefit amounts, which can often be adjusted over time. A portion of your premium payments enters into a money worth account within the policy. This account grows on a tax-deferred basis. This means you do not pay taxes on the gains as they accrue. This is the specifying function of IUL.
Insurance in Downey CAYou are not directly purchasing the index itself. Insurance provider use different techniques to compute the interest based on index performance. Typical techniques include yearly point-to-point, regular monthly point-to-point, or month-to-month averaging. The technique utilized can significantly affect the interest credited. This portion determines how much of the index's positive motion is used to calculate your interest credit.
PPO vs HMO Medical Coverage Review
Some policies use 100% and even higher involvement rates, but this often comes with other compromises. The majority of IUL policies have a cap, which is the optimum interest rate that can be credited to your money worth in an offered period, no matter how high the picked index carries out. If the index gains 15%, the participation rate is 100%, but the cap is 9%, your money worth would be credited with 9% interest (before costs).
Insurance in Downey CADiscovering the finest IUL carrier typically includes comparing present and historical cap rates, but this is simply one piece of the puzzle. This is an important protective feature of IUL. The floor is the minimum rate of interest your policy can make, even if the connected index experiences losses. The majority of typically, the flooring is 0%.
Some policies might use a floor somewhat above 0%, like 1%. Like other universal life policies, IUL provides versatility in premium payments. You can typically adjust the quantity and frequency of your payments within particular limitations, although paying insufficient premiums can threaten the policy's durability and money value development. It's right away clear that the interplay in between these aspects produces significant variation among the IUL policies used by different business.
An independent company like Insurance By Heroes is vital for comparing these detailed details throughout numerous top IUL suppliers. The search keywords "finest IUL for cash build-up" and "best IUL for retirement" emphasize this common interest.

Latest Posts

Low-Cost Individual Medical Insurance
Reviewing 2026 Term Life Insurance Premiums for Families

Indexed Universal Life IUL Policies for Security